Down Payment Assistance: What Gen Z and Millennial Buyers Need to Know
The housing market has shifted quite a bit, and a lot of the Gen Z and Millennial buyers I talk to are feeling it.
Right now, Millennials make up 26% of buyers and Gen Z are sitting at 4%. The median age of a first time home buyer is now 38! And the percentage of buyers who are doing this for the first time has dropped to just 21%. That's the lowest level since we started keeping track of these kinds of stats in 1981. Baby Boomers and Gen X are dominating the buyer market and this is part of why the market feels so competitive for younger buyers. Many are trying to enter at the same time that more experienced buyers are using equity to their advantage.
For younger buyers, especially those trying to purchase their first home, the biggest challenge isn’t always the monthly payment, it’s often just getting in the door in the first place. Between limited inventory and upfront costs, a lot of people feel stuck before they even start looking. We're starting to see a change in the inventory problem, but the downpayment and closing costs are still a hurdle for many.
A Market Divided: The Generational Gap
The housing market is currently defined by a sharp divide between existing homeowners with equity and new buyers trying to break in.
- Baby Boomers (42%) and Gen X (25%) are often leveraging housing equity to purchase their next homes, move closer to family, or downsize for retirement. This is why they're winning offers right now.
- Millennials (26%) have seen their overall market share decrease from the previous year, though older Millennials—now the highest-earning generation—are using their equity to move into larger home. This is where we see a majority of "move-up" buyers.
- Gen Z (4%) is a small but growing and confident segment, with many single females and unmarried couples redefining homeownership by prioritizing it over traditional milestones like marriage. This is the group that feels stuck the most.
For the 60% of younger Millennials who are first-time buyers, the primary hurdle is the "down payment wall."
The Solution: Down Payment Assistance (DPA)
While the market is tough, a powerful tool is helping many bridge the affordability gap: Down Payment Assistance (DPA). As of early 2026, there are 2,619 homeownership programs nationwide, with availability holding near record levels.
These programs offer an average benefit of approximately $18,000, which can reduce a borrower’s loan-to-value ratio by an average of 8.8%. This assistance not only helps with the initial down payment but can also cover closing costs, mortgage rate buydowns, and reductions in mortgage insurance costs.
In real terms, we've seen this cover most or all of a buyer's upfront cost. For some buyers, this is the diffrence between waiting 2 years and buying now.
Expanding Flexibility for Today’s Buyers
Most people assume these programs are only for low-income buyers, but that not actually true. The data shows that DPA is becoming more accessible than ever:
- Higher Income Limits: 62% of programs now have average income limits exceeding $100,000, and 10% of programs have no income limits at all.
- Every County Covered: Every U.S. county has at least one homeownership program, with over 2,000 counties offering ten or more.
- Targeted Support: There is a 32% year-over-year increase in programs specifically for first-generation homebuyers (those whose parents did not own a home).
- Diverse Housing Types: 81% of programs support newly constructed homes, and there is growing support for multifamily properties and manufactured housing.
Local Spotlight: Assistance in Texas
Here in Texas, organizations like the Texas State Affordable Housing Corporation (TSAHC) provide statewide programs such as "Homes for Texas Heroes" and "Home Sweet Texas". These programs offer assistance in the form of grants that do not have to be repaid (under most circumstances) or deferred forgivable second liens. To qualify, buyers generally need a minimum credit score of 620 and must meet specific income requirements. How to Get Started
If you are a Gen Z or Millennial buyer and have been putting off buying because of upfront costs, it's worth taking a closer look at down payment assistance programs.
Many buyers assume they won't qualify, or they underestimate how much assistance is available. Programs like those discussed above provide tools that can help you quickly see what you may qualify for. We often see buyers waiting longer than necessary because they don't have clear information.
If buying is something you're considering, the next step is simply to look at your options and run the numbers. You may be closer than you think. I can help point you in the right direction and connect you with lenders who can walk through your options and provide the information you need to to make a decision.
🏠Here to help you find your happy place!🧡
Amber Romitelli
REALTOR®
NextHome Realty Solutions BCS
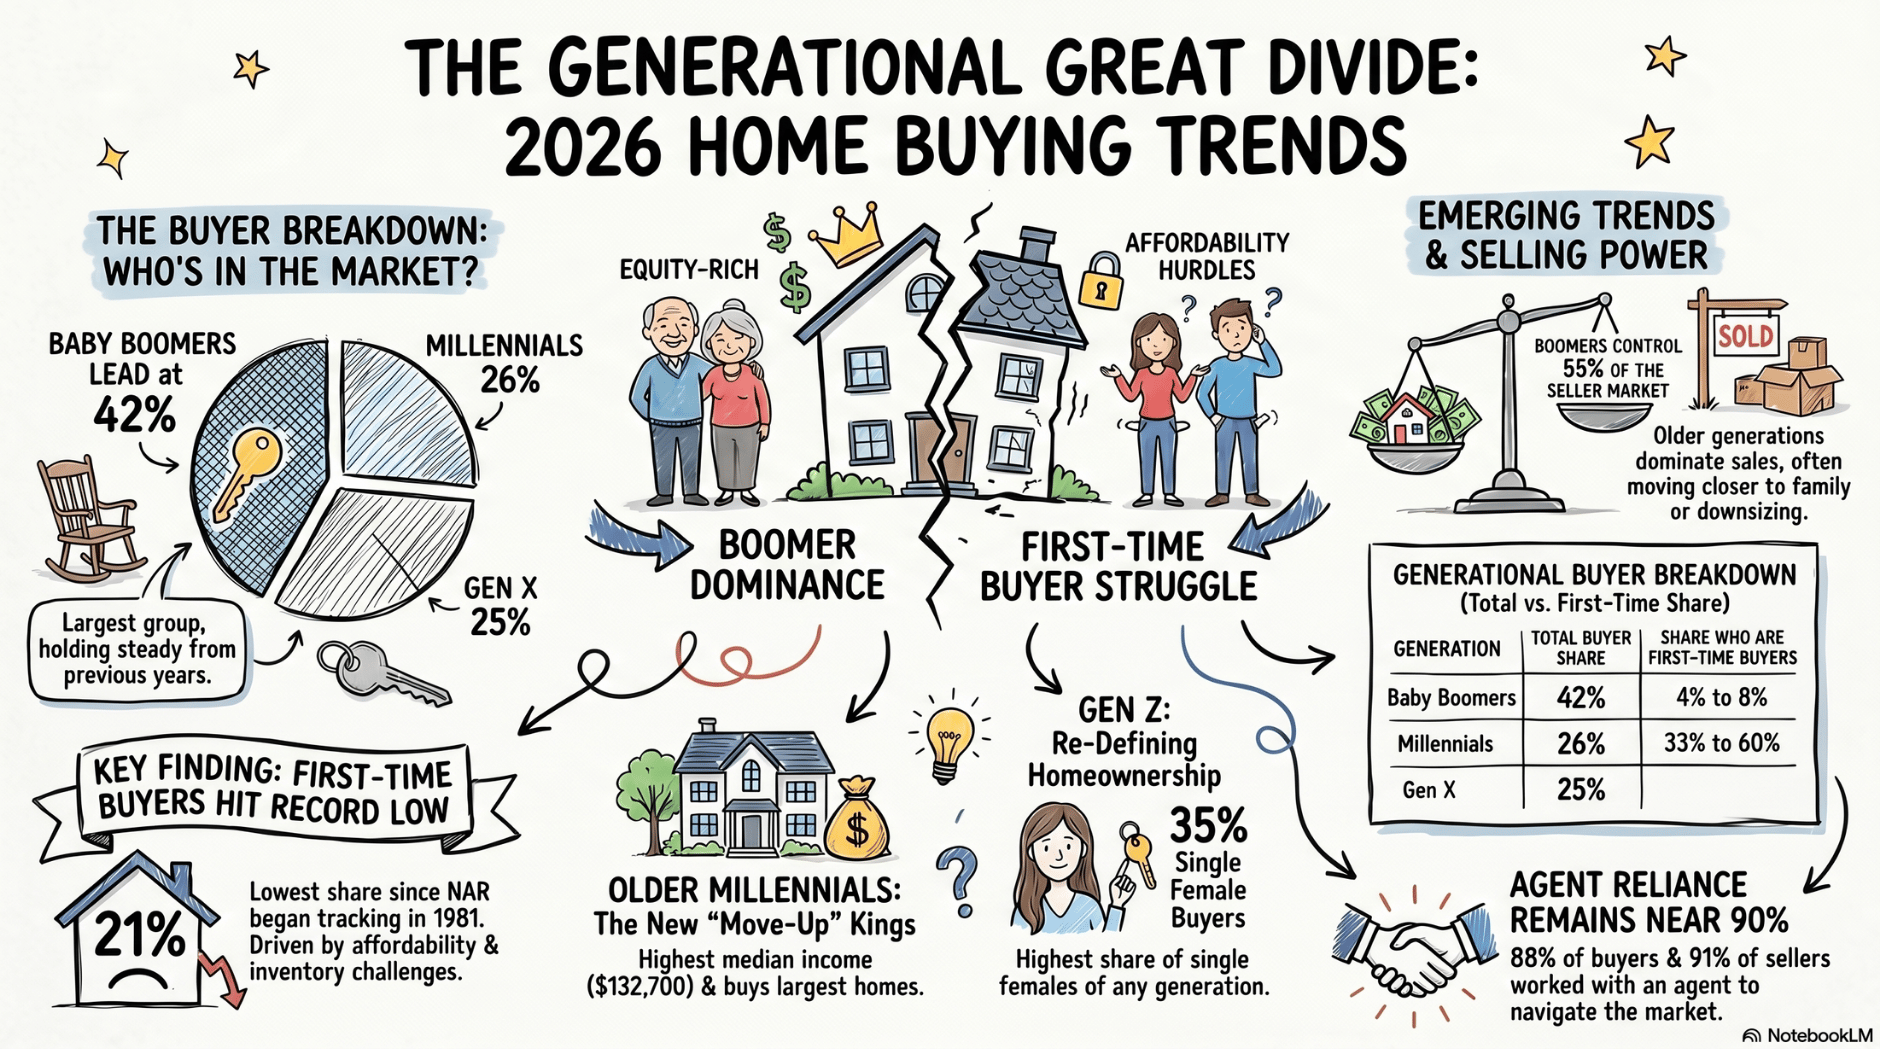
 © 2026 Bryan College Station Regional Association of Realtors. All rights reserved. Information deemed to be reliable but not guaranteed. The data relating to real estate for sale on this website comes in part from the Broker Reciprocitysm Program. Real estate listings held by brokerage firms other than NextHome Realty Solutions BCS are marked with the BR logo and detailed information about them includes the name of the listing brokers. Listing broker has attempted to offer accurate data, but
buyers are advised to confirm all items. Information last updated on September 21, 2026 11:42 PM UTC
Show More...
